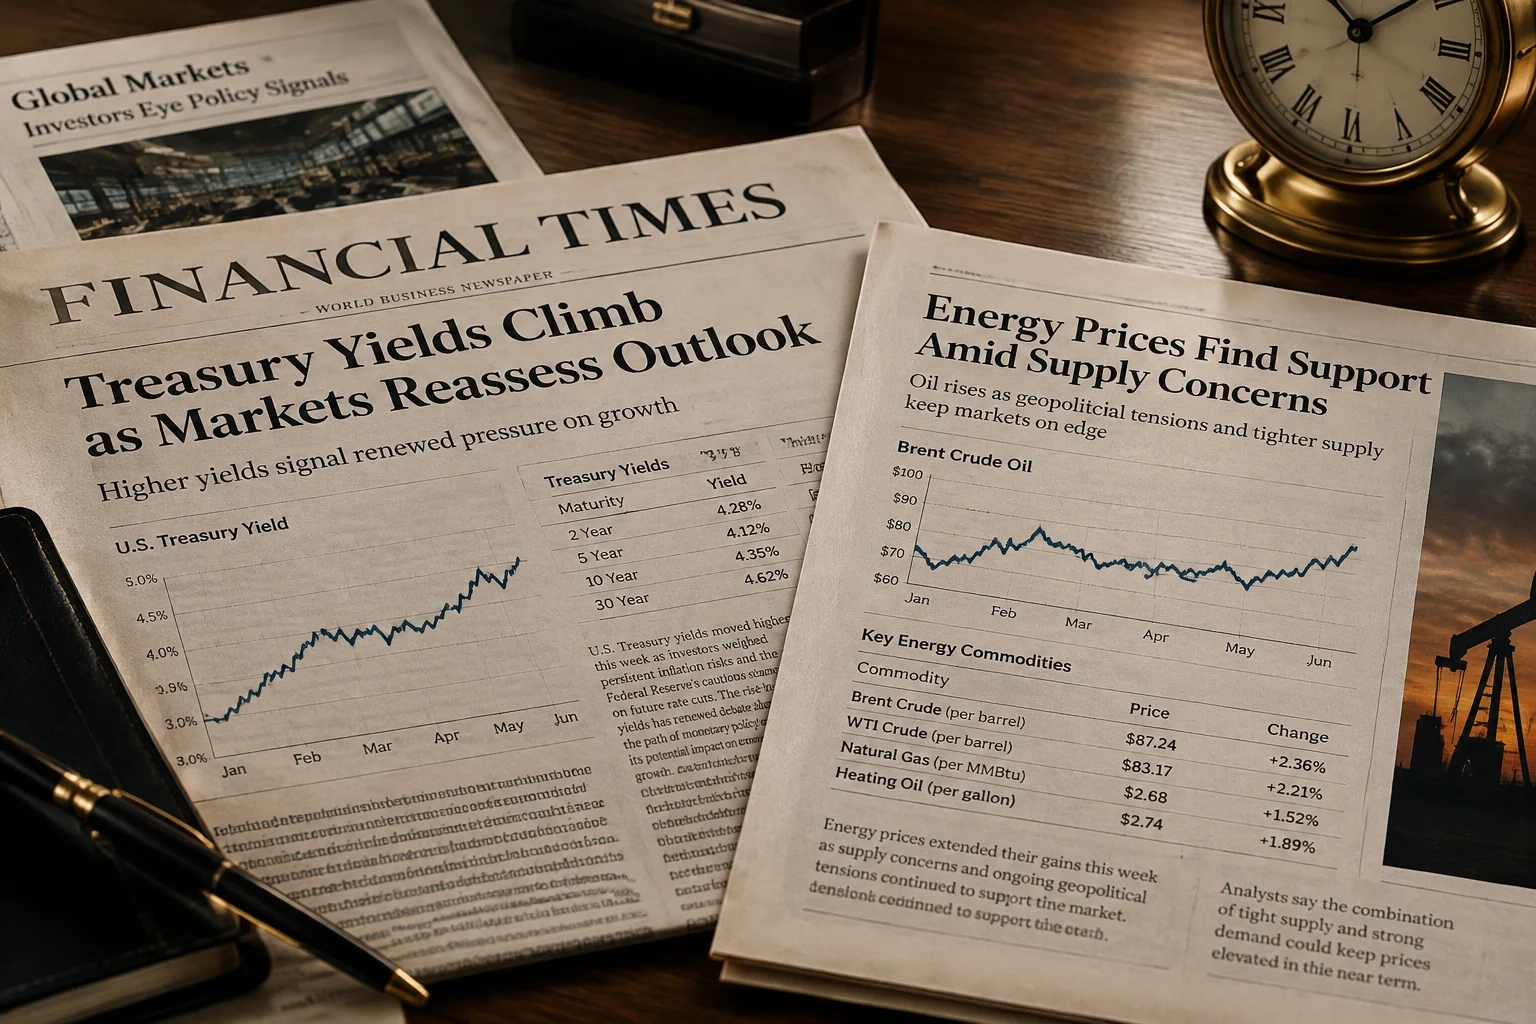
Sharp Curve Steepening Follows Sizable Treasury Debt Auctions
The US Treasury bond market experienced its most aggressive single-session sell-off in three quarters, driving benchmark 10-year yields sharply higher across institutional dealer books. The sudden slide in bond prices reflects an abrupt recalibration among bond market participants following heavier-than-anticipated sovereign coupon supply and stubbornly firm core inflation readings.
Primary dealers struggled to digest the flood of long-dated paper during recent Treasury refunding operations. With overseas central bank demand moderating and private asset managers demanding wider term premia, secondary markets witnessed rapid liquidation in 10-year notes and 30-year bonds, forcing yields up across the entire maturity spectrum.
Market Intelligence Briefing
Evaluate Fixed Income Software & Yield Analytics
Review our verified benchmarks of analytics platforms offering real-time duration stress testing and automated portfolio attribution engines.
Term Premia Rebound and Shifting Foreign Investor Participation
A critical element behind the bond market sell-off lies in the resurgence of positive term premia. Investors are no longer willing to hold extended maturities without substantial yield compensation, particularly as fiscal deficit projections indicate sustained high issuance levels into the coming fiscal quarters.
Key Analytical Takeaway
Institutional desks recorded an unusually weak tail across the 30-year bond auction, prompting rapid automated hedging liquidations that pushed real yields to their highest levels since early spring.
Cross-border demand from institutional reserve managers also signaled caution. Rising domestic yields in European and Asian sovereign debt markets have narrowed hedged yield advantages for foreign buyers of Treasuries, concentrating market absorption risks directly within domestic asset managers and pension funds.
“When duration risk meets consecutive record auction sizes, the clearing yield has to adjust higher until institutional balance sheets find acceptable risk-adjusted carry.”
Portfolio Implications Across Credit and Multi-Asset Allocations
The cascading pressure in government debt markets has quickly rippled across corporate credit spreads and equity valuation multiples. Because government paper serves as the fundamental risk-free benchmark, the rapid shift in borrowing costs forces immediate adjustments across diverse capital structures.
- —Investment-grade corporate credit spreads widened by 12 basis points as corporate issuers postponed new debt offerings.
- —Mortgage-backed securities suffered widening nominal spreads due to elevated prepayment uncertainty and reduced bank-portfolio absorption.
- —Equity risk premia compressed further, putting specific valuation downward pressure on dividend-sensitive and high-duration growth equities.
Market participants now await upcoming central bank commentary and updated dot plot projections to assess whether this sell-off represents a temporary supply adjustment or a fundamental structural shift in the baseline neutral rate regime.
Treasury Sell-off Analysis & Inquiries
Intelligence DeskAll News
Related Market Intelligence