Policy Realignment and the Mechanics of Further Monetary Tightening
The Federal Reserve interest rate hike enacted at the recent Federal Open Market Committee meeting delivers a definitive signal to global debt and equity markets. By raising the benchmark target corridor by twenty-five basis points to a restrictive band between 5.25% and 5.50%, the monetary authority underscores its intent to keep real policy rates well above neutral estimates. Central bank leadership highlighted persistent core service expenditures and elevated non-housing inflation prints as the primary drivers behind this incremental monetary tightening.
Market participants who anticipated an imminent plateau in rate adjustments must now recalculate discount cash flow frameworks across institutional portfolios. The decision clarifies that data dependence remains focused on structural wage metrics and sustained personal consumption expenditure indexes rather than transient softness in headline commodity inputs.
Market Intelligence Briefing
Evaluate Enterprise Financial Analysis Solutions
Review vetted corporate financial suites featuring automated sensitivity testing, real-time rate volatility modeling, and liquidity stress analysis.
Transmission Mechanisms Across Sovereign Yields and Credit Spreads
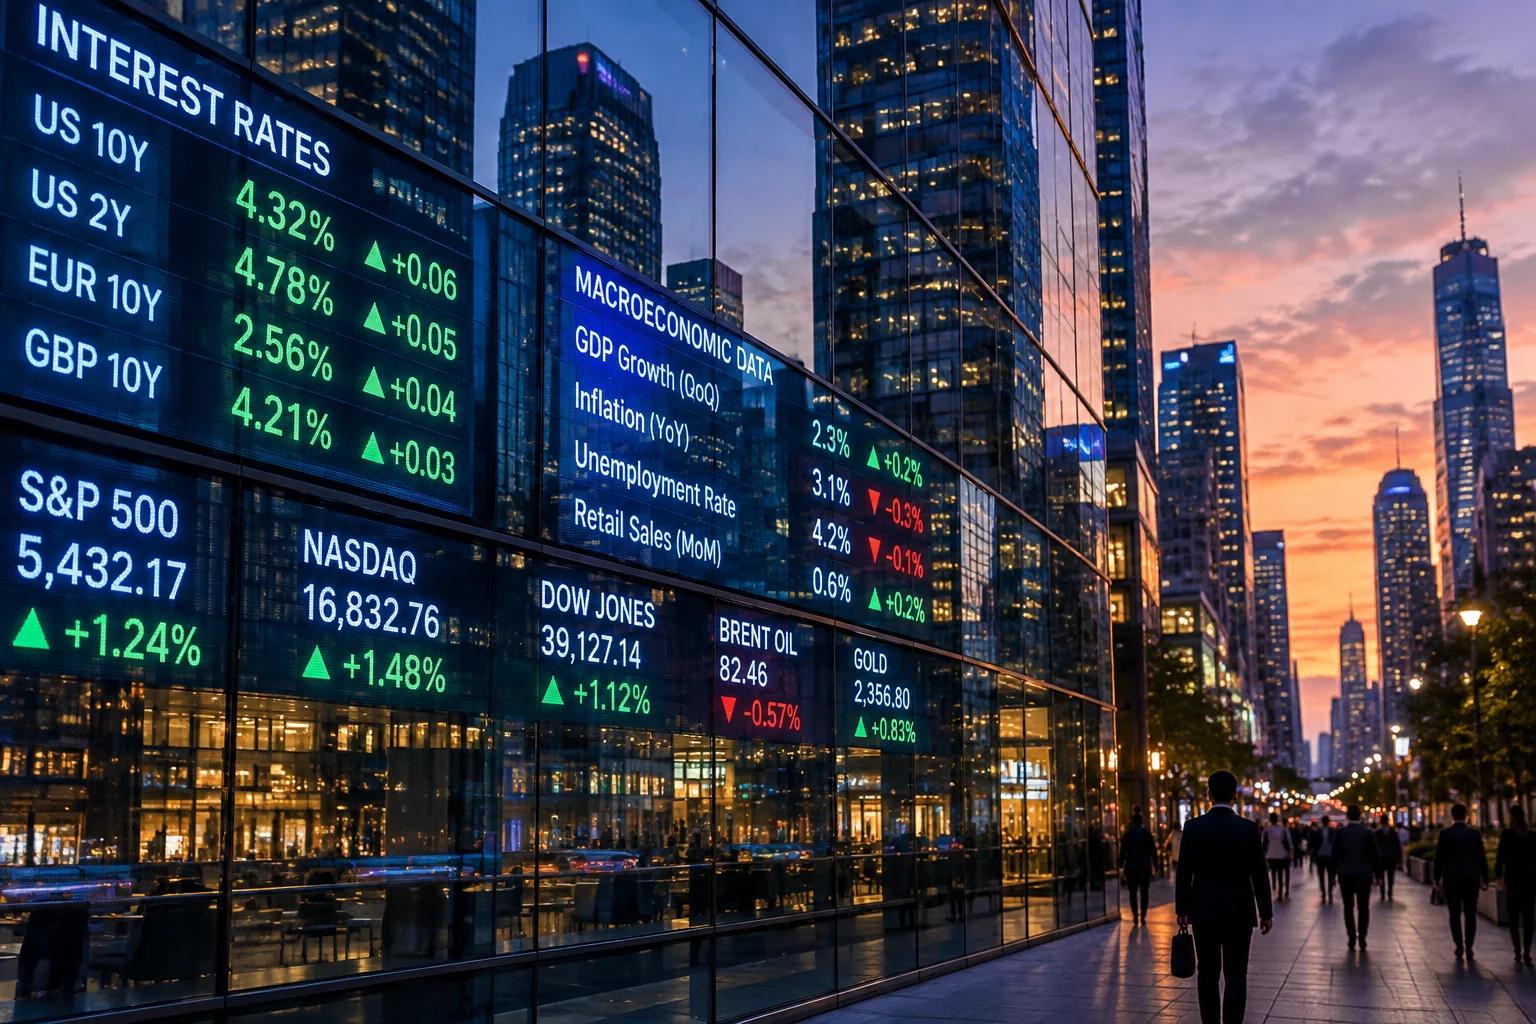
The transmission of this benchmark hike quickly permeated sovereign debt markets, with two-year US Treasury notes advancing fourteen basis points to settle at 4.88%. Yield curve inversion between the two-year and ten-year tranches expanded further, reflecting ongoing market expectations of growth deceleration over intermediate horizons. Meanwhile, investment-grade and high-yield corporate credit tranches recorded immediate spread widening as institutional syndicates repriced refinancing obligations.
Key Analytical Takeaway
The ongoing expansion of the policy rate corridor raises the hurdle rate for speculative investments, directly incentivizing balance sheet consolidation and shortening effective portfolio durations across enterprise debt management.
Commercial banking institutions responded synchronously by lifting prime lending reference figures. Consequently, variable-rate commercial and industrial loan facilities will absorb increased interest carrying burdens, requiring corporate treasurers to run tighter liquidity margins and evaluate debt-servicing capability against dynamic revenue streams.
“Sustained policy tightness compels financial institutions to recalibrate discount cash flow variables, directly elevating the hurdle rate for capital expenditure across corporate treasuries.”
Strategic Balance Sheet Adjustments for Institutional Treasurers
Operating within a prolonged higher-for-longer interest rate framework necessitates decisive adjustments in enterprise cash management and working capital allocation. Financial planning and analysis divisions are moving beyond static quarterly budgeting models, choosing continuous scenario simulations to manage funding variables:
- —Duration Risk Compression: Proactively staggering debt maturity profiles and restructuring near-term bond renewals into shorter, flexible credit facilities.
- —Cash Equivalents Optimization: Deploying idle operating reserves into high-yielding Treasury bills and reverse repurchase facilities to maximize risk-free cash returns.
- —Covenant Stress Testing: Modeling debt-service coverage ratios against expanded terminal rate parameters to safeguard against liquidity triggers.
Ultimately, this hike illustrates that monetary conditions will remain restrictive until disinflation indicators decisively converge toward the statutory two percent annualized objective. Corporate financial teams that integrate automated rate sensitivity modeling into day-to-day operations will navigate this prolonged borrowing cost cycle with superior balance sheet resilience.
Frequently Asked Questions Regarding the Fed Rate Hike
Intelligence DeskAll News
Related Market Intelligence & Policy Reports