Dual Mandate Calibration Amid Commodity Price Volatility
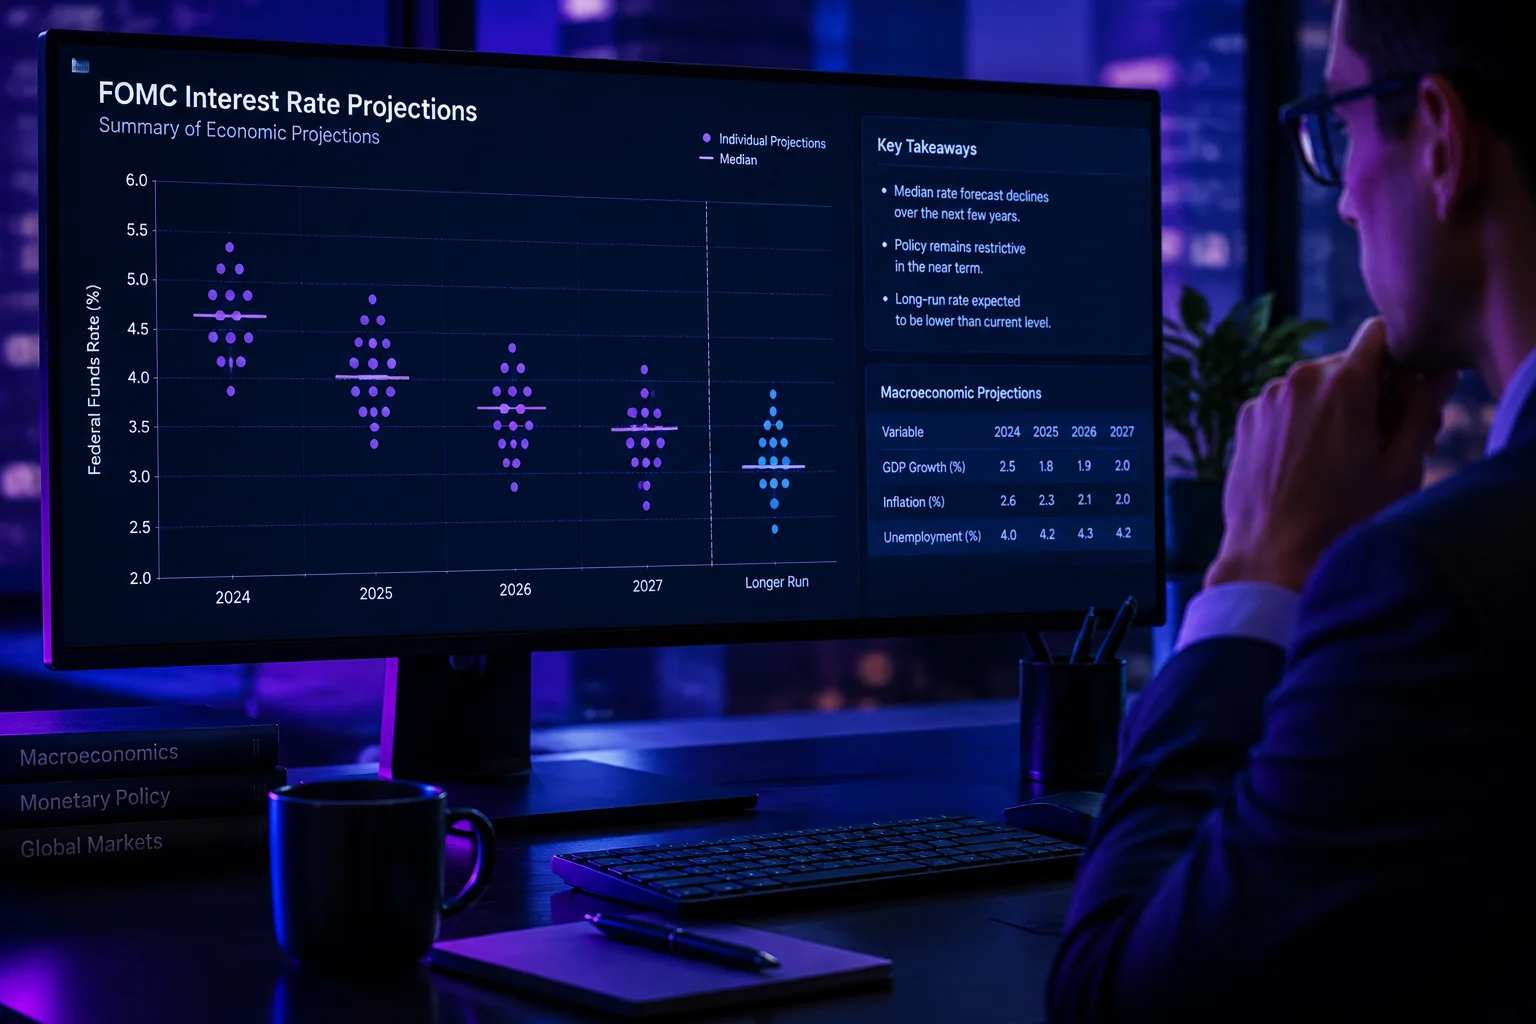
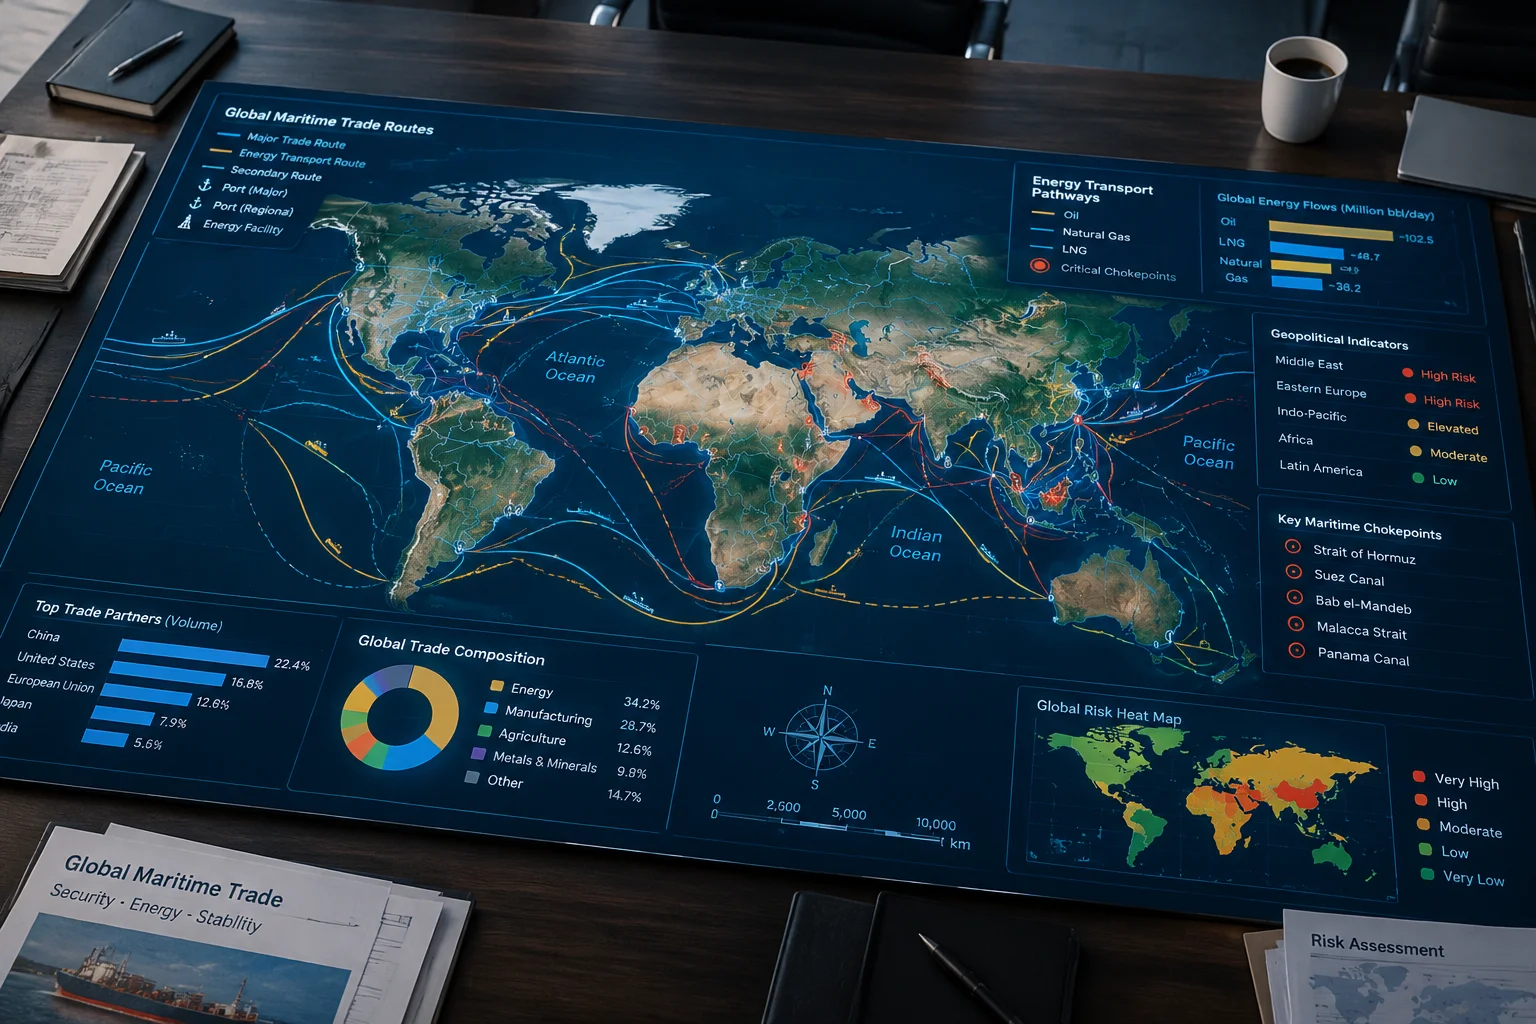
The latest semi-annual Monetary Policy Report from the Federal Reserve confirms a cautious yet resolute stance as policymakers balance price stability against sustained employment targets. Headline inflation figures moderated over the past two quarters, yet stubborn pressure in core non-housing services and sudden disruptions in global commodity corridors complicate the path toward the target two-percent baseline. The Board notes that overall consumer spending exhibits durable momentum, though corporate lending demand reflects heightened sensitivity to borrowing expenses.
Financial conditions across domestic markets tightened moderately throughout mid-2026, driven by higher term premiums on sovereign debt and strict balance sheet management. The Federal Open Market Committee underscores that policy decisions remain strictly contingent on cumulative incoming metrics rather than predetermined multi-meeting rate reductions. Industry analysts monitoring industrial balance sheets must account for persistent cost divergence, where raw material volatility offsets modest wage stabilization across regional supply networks.
Balance Sheet Normalization and Credit Supply Constraints
Central to the current policy framework is the ongoing runoff of Treasury securities and agency debt, commonly termed quantitative tightening. Commercial banking reserves contracted in an orderly fashion without destabilizing short-term money markets, yet regional institutions face deposit beta adjustments as savers seek elevated short-duration yields. Commercial real estate exposure and tightening underwriting guidelines continue to restrict credit expansion for mid-sized enterprises.
The transmission mechanism of monetary restraint continues to display uneven sector impacts. Residential housing transactions reflect subdued turnover caused by elevated mortgage rates, whereas technology and automated manufacturing investments show steady capital commitments. Corporate liquidity buffers remain adequate across top-tier conglomerates, yet smaller regional operators report strained interest coverage ratios that could constrain payroll growth if borrowing costs remain elevated through early 2027.
Key Forecast Benchmarks & Indicators
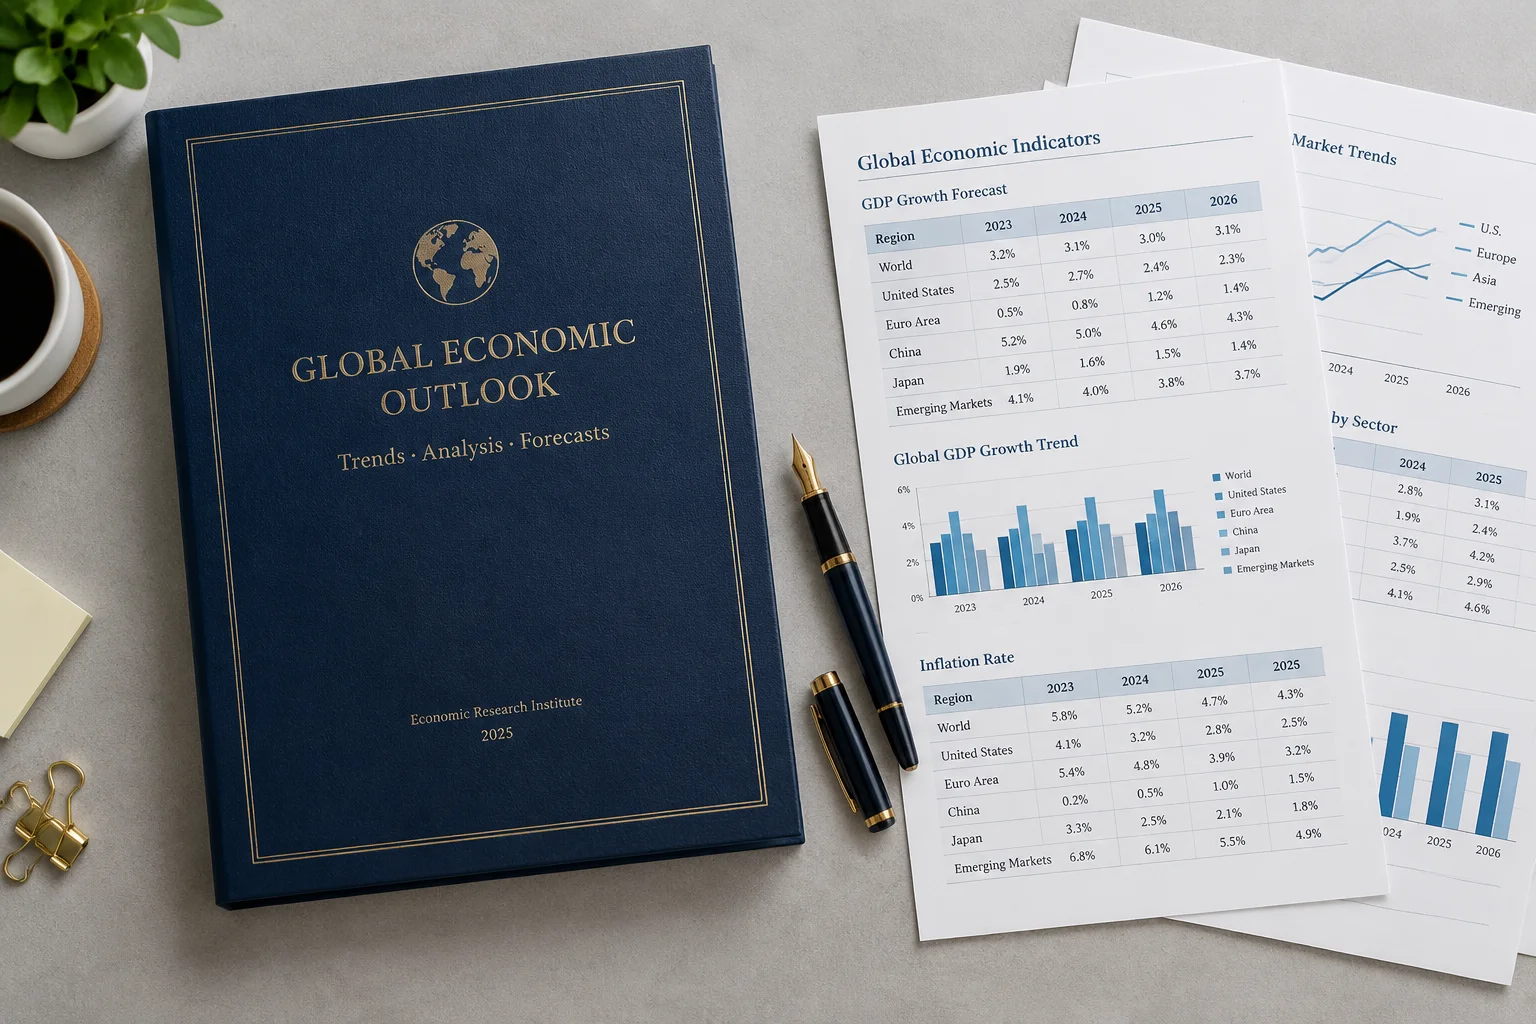
Model Metrics| Indicator | Target Period | Baseline Estimate | Validation Status |
|---|---|---|---|
| Federal Funds Target Range | Q3-Q4 2026 | 4.75% – 5.00% | Restrictive Baseline |
| Core PCE Price Index | Year-End 2026 | 2.6% Projected | Disinflation Track |
| Real GDP Expansion Rate | Annualized 2026 | 1.9% – 2.1% | Moderate Expansion |
| Monthly QT Runoff Cap | Current Quarter | $60B Treasuries / $35B MBS | Orderly Liquidity Drain |
Critical Policy Implications for Corporate Balance Sheets
Enterprise financial planners and portfolio managers face distinct strategic considerations as the Fed maintains higher real interest rates to ensure durable disinflation. Scenario testing must account for three core operational dynamics highlighted throughout the testimony:
- — Debt Refinancing Schedules: Corporate borrowers must prepare for sustained higher refinancing costs as maturities issued during historic low-rate cycles come due, elevating interest burden ratios.
- — Commodity Pass-Through Resistance: Consumer elasticity limits the ability of retailers and manufacturers to pass unexpected wholesale commodity spikes directly into shelf pricing.
- — Labor Market Rebalancing: Job creation is normalizing toward sustainable historical averages without widespread layoffs, preserving aggregate wage support while cooling wage-push inflation.